The infrastructure layer for delinquency operations, before and after charge-off.
Debt Digest is the shared receivables workflow platform banks embed between their core and recovery operations. Your brand on every customer touch, FFIEC-aligned, with participant identity and audit-log integrity by default. Your team owns strategy and approves each activated workflow; the platform enforces the configured controls. Subscription only: no contingency or percentage of recovery.
See how the compliance works · your team presses send on the outreach you place.
Regional and money-center banks. Institutional-grade by default.
People can enroll before you join. Their analysis comes with them.
Customers can enroll and analyze their accounts before your bank joins the rails. When you join, anyone who flagged you appears in your inbox, and you connect each one by placing your own record. Counts only: this page does not name any consumer. $2.50 per active account per month. Never a percentage of recovery. Consumers are not charged that fee.
- People can enroll before you join.
- Their account analysis comes with them.
- $2.50 per active account per month, never a percentage of recovery.
Recovery surfaces
Two recovery surfaces · one platform layer · ownership and authority explicit throughout
Pre-charge-off intervention
Reach customers in the 45 to 115 DPD window
Run outreach before an account hits your FFIEC URCC charge-off timeline, on the cadence your portfolio runs on. Your team presses send on the outreach you place. How the timing works.
Settlement infrastructure
The workflow, not the counterparty
When a customer or their representative wants to settle, it happens in one place: offers, counters, and e-sign, all on screen, with payment confirmation once your payment rail is connected at pilot setup. Every offer is checked against the floor you configure, so nothing clears below your number.
Multi-party operations
Agencies, firms, and in-house in one workspace
When a customer retains a settlement firm or you place with an agency, your team works the account through one settlement workspace. The counterparty submits an offer; your configured floor auto-approves or routes it for review. E-sign and remittance in the same thread.
Live today, and growing as banks pull us forward.
Your operations team decides what goes out.
The outreach you place goes out when your team presses send. The platform prepares each one in your name, and the send is appended to the hash-chained audit log. Flat per-account subscription: no contingency, no percentage of recovery.
-
1
Import your accounts
Export from FIS, Jack Henry, Fiserv, or your core. We build a per-account profile and mark each account as Not Yet Contacted.
-
2
Review who hasn't been contacted
Filter to the Not Yet Contacted queue. See the channel recommendation, which your operator can override, before your team sends. The onboarding wizard is where your team reads the notice itself. Where the consumer’s state is on file, texts outside that consumer’s local quiet-hours window are blocked; where it is not, an Eastern-time window applies. Every step is auditable.
-
3
Click to send: you're in control
One button. Your outreach goes out under your bank's name, your reply-to, your brand. The hash-chained audit log captures the sending organization, the time and the batch.
Creditor-initiated
How the three paths actually compare.
Most creditors pick one of three delinquency strategies. Here's what each costs, and what you give up.
| Attribute | Traditional agency | In-house collections | Debt Digest |
|---|---|---|---|
| Pre-charge-off intervention | No | Partial | Yes, 45–115 DPD |
| Typical cure / recovery rate | 10–18% | 15–20% | Measured against your baseline |
| Customer relationship and participant control | Often broken | Varies by agent | Preserved; roles and authority are recorded |
Your legal team wrote our spec, not the reverse.
Quiet hours, dispute holds, and frequency counters run in the send path where this page names them. Representation checks fail closed on collector and firm send paths; the creditor path skips that check when identity is incomplete. Legal duties still follow each identified participant's actual role and conduct.

FDCPA §1692eFDCPA §809(a) Validation notice
FDCPA §809(b) Dispute pause
Reg F §1006.6 Outreach windows
Reg F §1006.34 Itemization
FFIEC URCC 180/120-DPD charge-off rule (banks)
OCC Bulletin 2020-10 third-party risk
TCPA 47 U.S.C. §227 Quiet hours
Infrastructure you embed, not an agency you outsource to.
Banks already run their stack on embedded infrastructure layers. You own the strategy and the customer; the layer handles the hard, regulated plumbing. Debt Digest is that layer for delinquency operations.
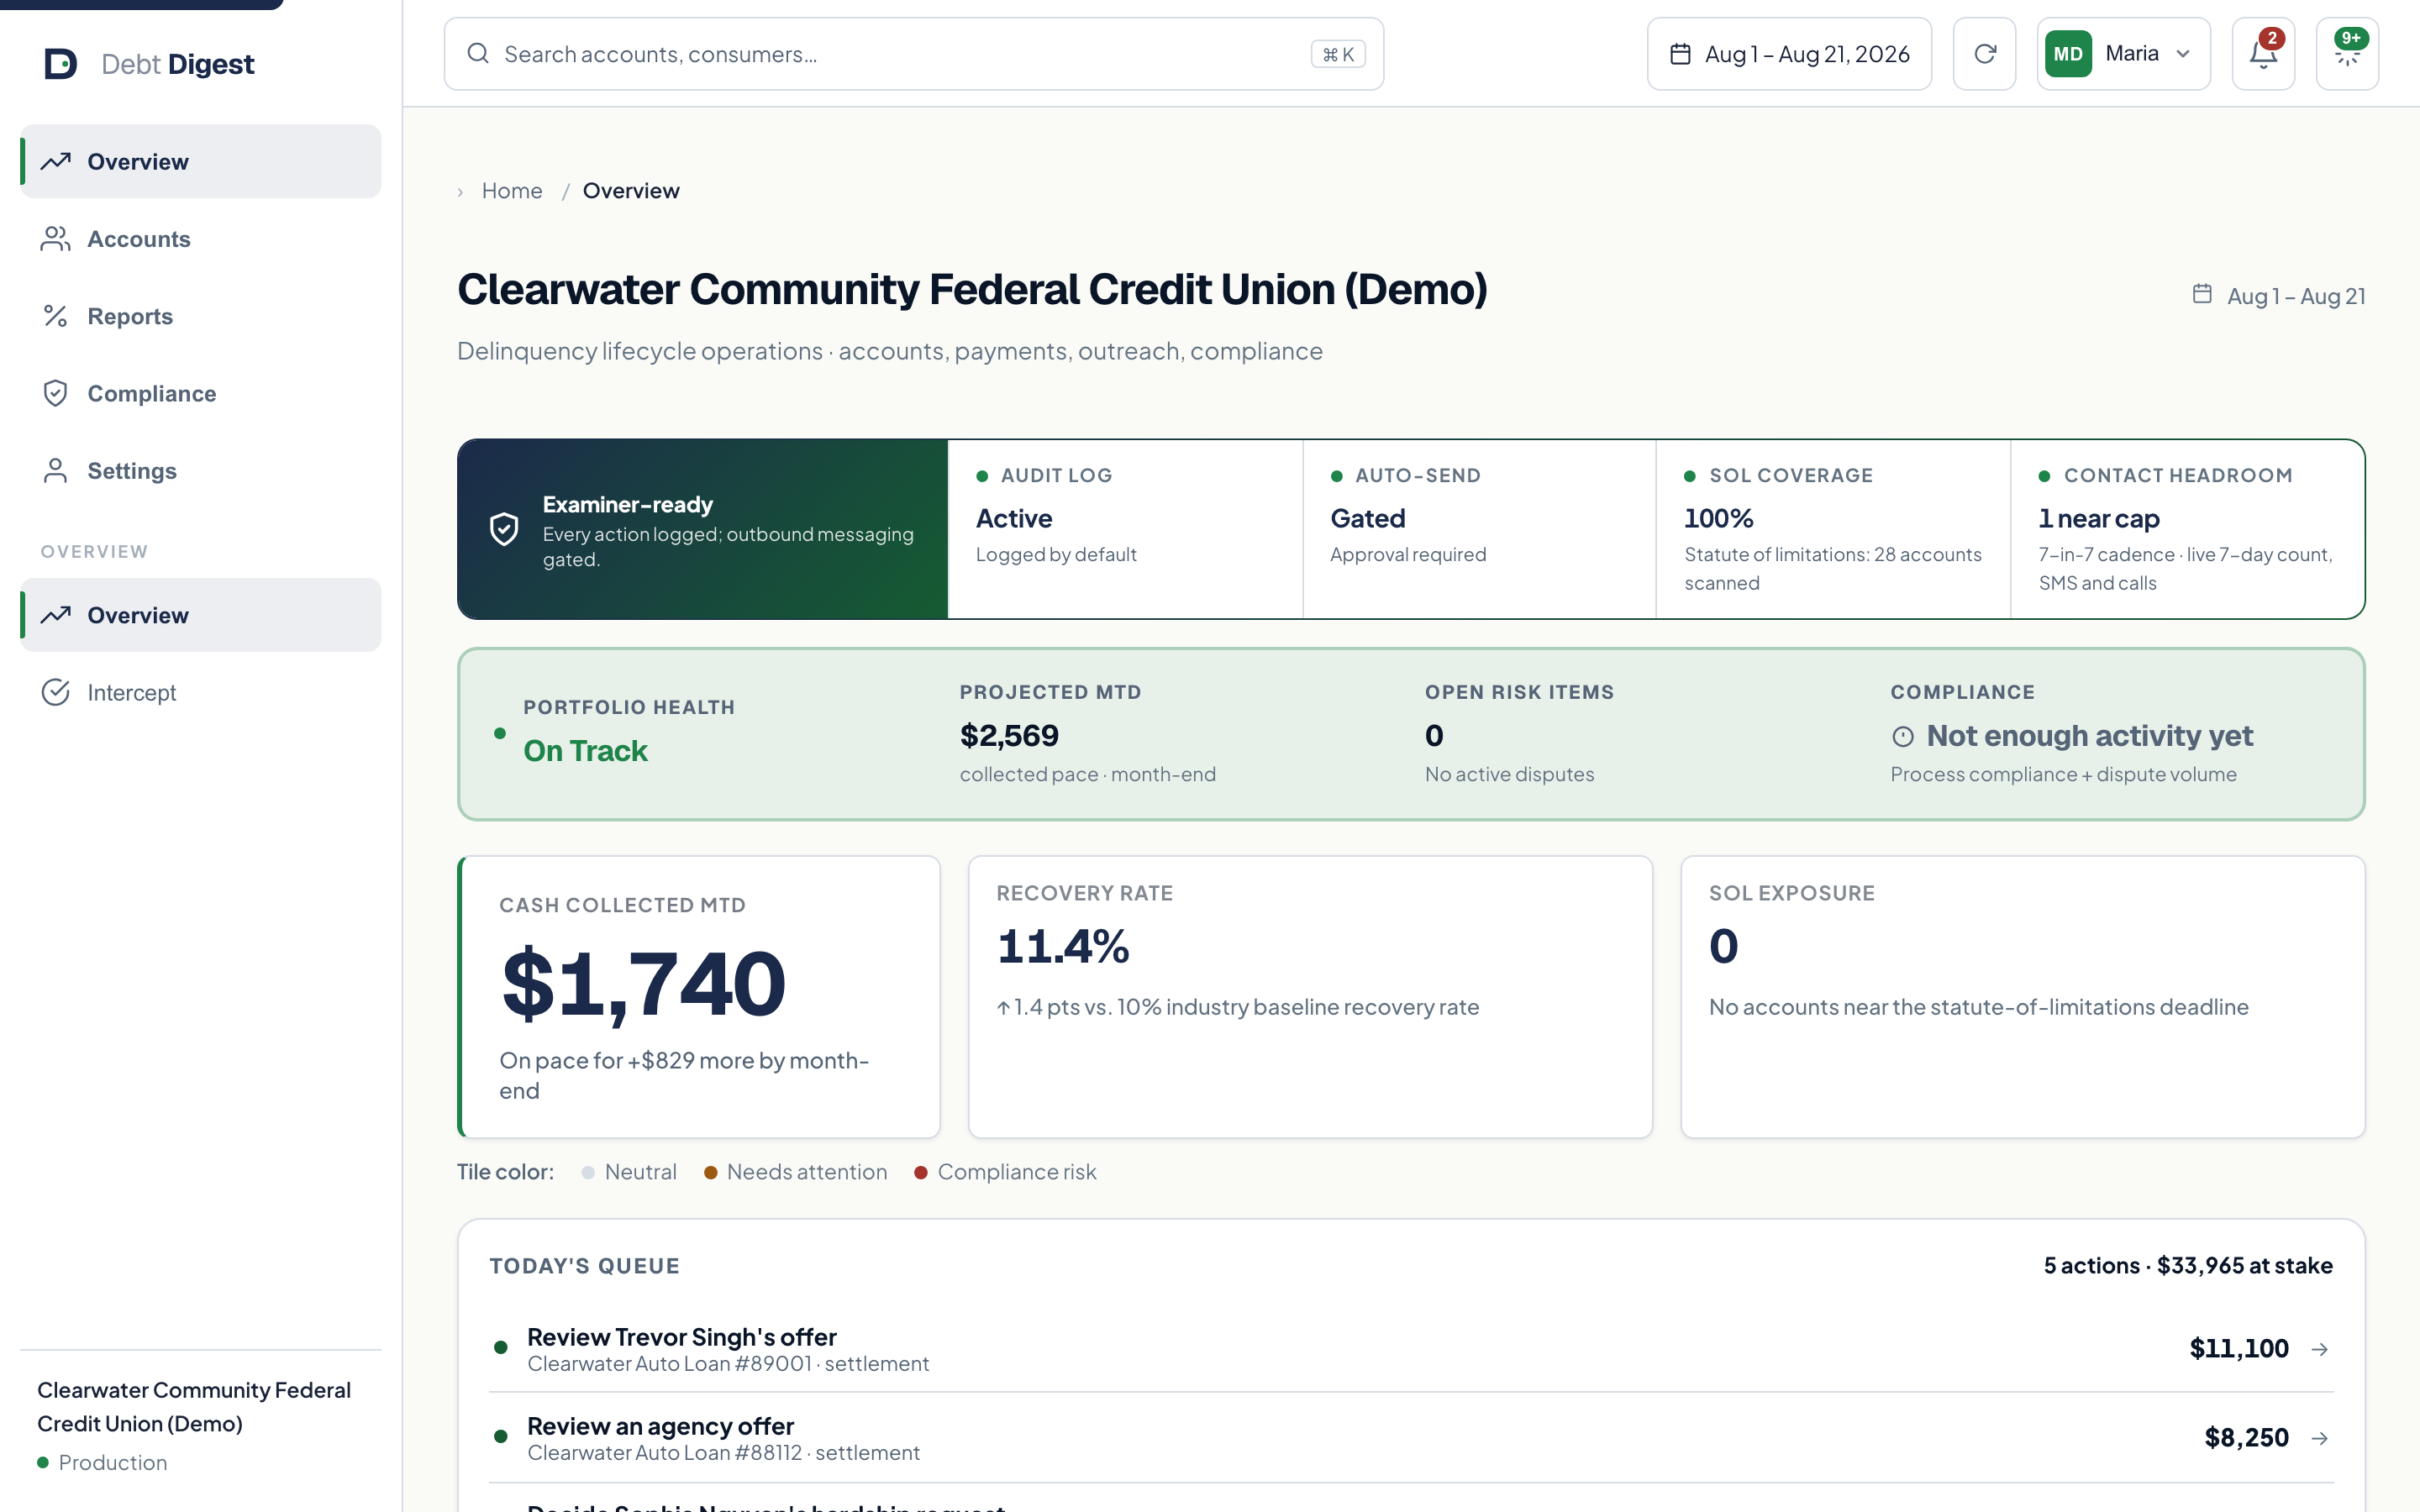
See Debt Digest in action.
The three surfaces your delinquency operations team will actually use during the pilot.
| Customer | Balance | DPD | Status | Outreach |
|---|---|---|---|---|
| J. Martinez | $4,200 | 67 | Delinquent | Plan accepted |
| S. Chen | $12,900 | 104 | 91–115 | Pending |
| M. Williams | $8,400 | 51 | Delinquent | Plan viewed |
| A. Patel | $2,650 | 0 | Cured | 60-day current |
| Customer | Balance | Offer | Discount | Status | Days left |
|---|---|---|---|---|---|
| James T. | $4,200 | $2,940 | 30% | Pending | 14 days |
| Sarah M. | $8,900 | $5,340 | 40% | Accepted | n/a |
| David K. | $15,400 | $9,240 | 40% | Declined | n/a |
| Ana P. | $2,800 | $1,960 | 30% | Accepted | n/a |
Ready to see your portfolio here?
Request a pilotSix surfaces. One workspace. Built for the regulator over your shoulder.

Start on the dual-trigger free tier. Keep going only if the measured baseline holds.
Non-exclusive. Champion-challenger structure. No upfront platform fee. All accounts and data returned to you on exit, with no lock-in.
Binding pilot agreement. Covers your baseline, pricing, and the dual-trigger free-tier exit. Your counsel reviews in one session.
One CSV from FIS, Jack Henry, Fiserv, or your core. We create customer records and seed outreach profiles per account.
Customers self-resolve in the portal. Weekly status reports. Recovery rate vs your baseline updates live in your dashboard.
The evaluation is free until you place 100 accounts or 30 days pass, whichever comes first, and does not convert automatically. Continued paid access begins only after a separately accepted subscription order form. Standard pricing is $2.50 per active account per month with a $1,500 monthly floor; there is no per-resolution, outcome, contingency, or percentage-of-recovery fee.
At what recovery rate does Debt Digest pay for itself? Almost any.
Four numbers from your last 12 months. See how the platform subscription compares against the incremental recovery your team (or a 25–40% contingency agency) would have left on the table anyway.
Replace the seed with your own 12-month history on the same DPD bucket, or the default in your order form. We report recovery lift against that baseline; it is an ROI-reporting benchmark, never a fee trigger. Cure definition: 0 DPD + 60 days current.
Illustrative. The evaluation is $0 until 100 accounts or 30 days, whichever comes first, and does not convert automatically. A separately accepted standard order form is $2.50 per active account per month with a $1,500 monthly floor. No per-resolution or percentage-of-recovery fee.
Flat per-account subscription that scales with your portfolio, not your recovery.
No per-seat fees. No setup charges. No percentage of recovery. Flat per-account subscription billed monthly.
- Guided onboarding on your brand
- Recovery lift reported against your own baseline
- CSV placement, customer portal
- Real-time dashboard + audit export
- Founder-led weekly review
- Everything in Pilot
- Outreach intelligence + operator override
- Post-charge-off recovery available
- Online settlements with outside firms
- API access + webhooks
- Everything in Standard
- Branded entry domain on your own subdomain
- FIS / SS&C / Jack Henry core integration
- Dedicated compliance + success operator
- State expansion handled by DD
Cure definition: account returns to 0 DPD and remains current 60+ days. This is how your recovery ROI is reported, not a billing trigger. Your baseline (your own 12-month history, or the default in your order form) is a reporting benchmark, never a fee basis. Payment flow: customer pays you directly. You pay Debt Digest a flat monthly subscription. No percentage of recovery. Detailed terms on /pricing.
Plain answers to the four questions every procurement deck includes.
No spin. If a question doesn't have a clean answer yet, we say so.
Built by someone who has lived the delinquency lifecycle from the consumer side.
Debt Digest's founder works at a debt-settlement law firm representing people being sued for credit-card debt. Every day, hundreds of clients walk in scared, confused, and convinced they are the only one who is behind. Almost all of them want to pay. They just do not know how, and every collections call they have had made it worse.
The usual model is built around post-charge-off agencies who get paid to pressure. Debt Digest moves the moment of help earlier, takes the pressure out of it, and gives customers a path they can actually take.
This is not a collections company trying to sound nice. It is the product we wish existed for every client we have represented.
See the integration plan and savings estimate in 30 minutes.
Send us the size of your 45 to 115 DPD population. We'll model your recovery lift, pilot economics, integration scope, and pilot rollout plan at no cost, no obligation.
Your data. Your settlement floor. Your customer relationship.
We are the infrastructure layer. Your account ownership, operating authority, brand, sender identity, settlement decisions, and payment destination remain explicit in the shared record.